Terms and Conditions
The agreement between you and iSmart International Ghana Limited when you use iSmartPay. Start with the key points and the parts that apply to you. The full agreement is below.
iSG-LEG-00001 · Version 1.00 · 12 August 2026
The key points
This summary is provided for convenience. It is not part of the Agreement and does not change it. If the summary and the Agreement differ, the Agreement applies.
- We are licensed and supervisediSmart International Ghana Ltd is licensed by the Bank of Ghana as a payment service provider. Your money moving through us is subject to that supervision.
- Your money is kept separate from oursFunds we hold for you sit in designated accounts, are not used for our own purposes, and are reconciled every working day.
- We must know who you areThe law requires us to verify identity before you can transact, and to keep verifying. If you will not provide what we need, we cannot serve you.
- Some payments cannot be reversedMobile money and interbank credits, and value-added services such as airtime, are delivered instantly and generally cannot be recalled. Check the destination before you confirm.
- You can complain, and then escalateWe answer complaints within published timelines. If you are not satisfied, you may take the matter to the Bank of Ghana. Nothing in this Agreement removes that right.
- We can suspend or close an accountWe can, and sometimes must, restrict an account — for legal reasons, for risk reasons, or where these Terms are breached. Where the law permits, we tell you why.
- Fees and limits can changeWe give notice before a change takes effect, except where a change is required by law or by a regulator, in which case we tell you as soon as we can.
Which parts apply to you?
Part A applies to everyone. Then read the Schedule for how you use iSmartPay, and the Annex for each payment method.
You run a business
This Schedule applies to you if you are accepted by us to accept payment or make disbursement through the Services. It is in addition to Part A, and prevails over Part A where they conflict.
You use the wallet app
This Schedule applies to you if you hold an iSmartPay Wallet or use the iSmartPay application to pay, receive or hold value. It is written for individuals and is in addition to Part A.
You build on our API
This Schedule applies to you if you access the iSmartPay API, the sandbox, or any interface we publish, whether for your own business or on behalf of a Merchant.
- Instructions are yoursWe act on instructions received through your Account or credentials. Once a Transaction is authorised and submitted, you cannot generally cancel it.
- Check before you confirmYou are responsible for the accuracy of a destination — a mobile number, an account number, a reference. Value sent to a wrong but valid destination is often unrecoverable.
- FinalityMobile money credits and GhIPSS Instant Pay credits are irrevocable once posted. We will attempt a recall where value is misdirected, but a recall is a request that the receiving institution is not obliged to grant.
- Pending is not successA Transaction shown as pending has not completed. Do not release goods or services on a pending status.
- Limits applyTransaction, daily and balance limits apply. They are set by us, by the Bank of Ghana and by Providers, and they may change without notice where required by law or by a Provider.
- We may refuse or delayWe may refuse, delay, hold or reverse a Transaction where we are required to by law, where we suspect fraud or financial crime, where a limit is exceeded, where a control requires it, or where a Provider declines it.
- RecordsOur records of a Transaction are the primary evidence of it. We retain them for at least seven years.
If something goes wrong.
We would rather resolve a problem than argue about it. You can go to the Bank of Ghana at any point.
- Tell usContact us on any channel in clause 1. We log the complaint the day we receive it, whoever receives it.Same day
- AcknowledgementWe give you a case reference, the name of the person handling it, and the date by which you will hear from us.1 Business Day
- Investigation and determinationWe investigate on the transaction record and give you a determination in plain language, with the reason and what we will do.Within the timeline published by the Bank of Ghana for payment service providers
- Internal escalationIf you are not satisfied, ask us to escalate. A senior officer who was not involved reviews it.10 Business Days
- Bank of GhanaYou may complain to the Bank of Ghana. We tell you this in every determination and we will give you the contact details.At any time
- ArbitrationA commercial dispute not resolved above is referred to arbitration by a single arbitrator, seated in Accra, conducted in English, under the Alternative Dispute Resolution Act, 2010 (Act 798). The award is final and binding.On referral
- CourtsEither party may apply to the courts of Ghana for urgent injunctive relief, or to enforce an award. Otherwise the courts of Ghana have exclusive jurisdiction over any matter not subject to arbitration.At any time
If you use iSmartPay personally:If you are an individual using the Services for personal purposes, nothing in this clause requires you to arbitrate, and nothing in it prevents you from bringing a claim in the courts of Ghana or complaining to the Bank of Ghana or to the Data Protection Commission.
Who we are and how to reach us.
- Registered officeG-286-2423, Rabat Plot 2 near Gethsemane Cemetery, East Legon, Zaire Street
- Company registration numberCS681282015
- Bank of Ghana licencePSP Medium
- General supportEmail: info@ismartghana.comsupport and support telephone: 0303944139
- Complaintscustomersupport@ismartghana.com; see clause 17
- Data protection enquiriesThe Data Protection Officer at M.MOHAMMED@ismartghana.com; see the Privacy Notice iSG-LEG-00002
- Legal noticesThe Head of Legal and General Counsel at legal@ismartghana.com and at the registered office
The full Terms and Conditions.
Every clause of the agreement, as approved. Search for a word or open the part you need.
About This Agreement
1.1 Structure of This Agreement
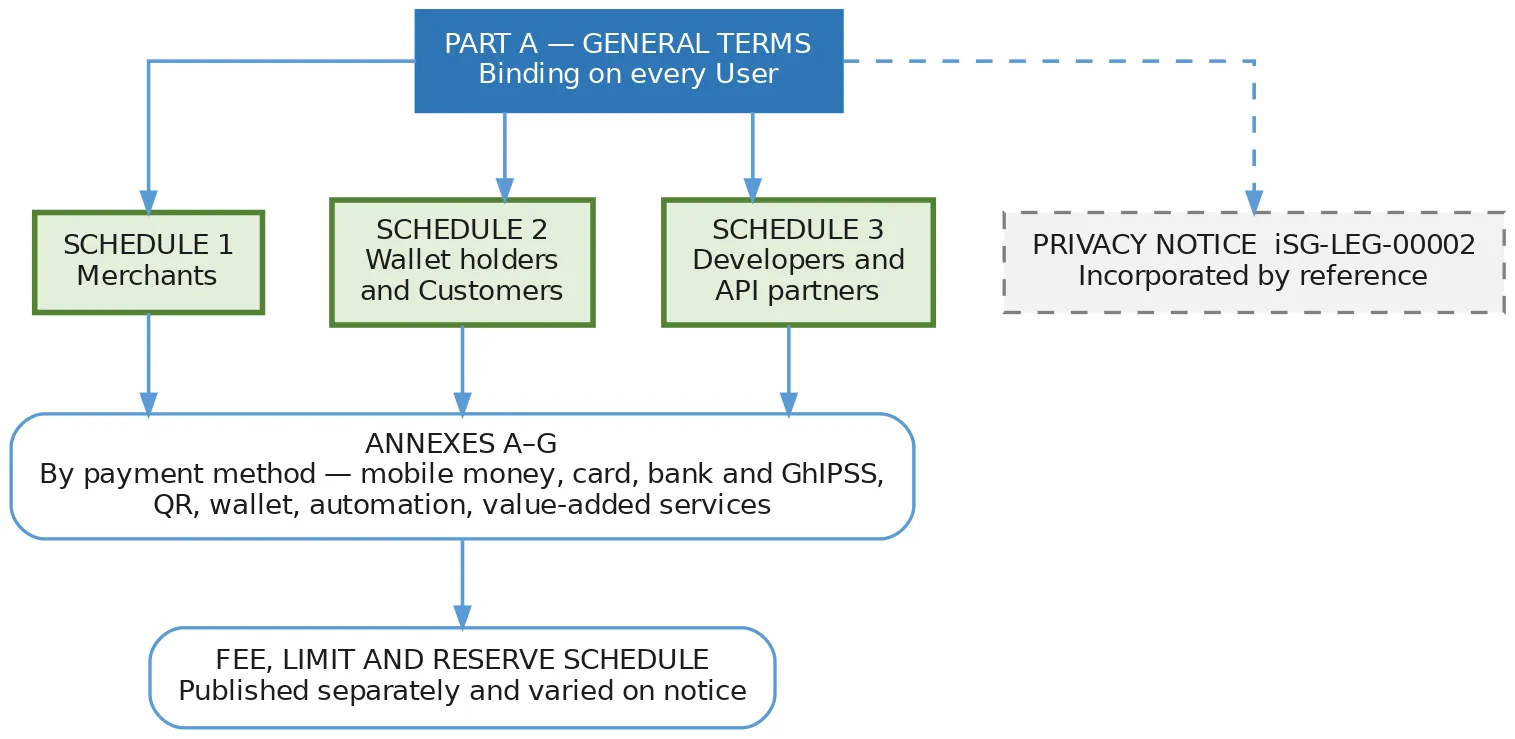
Figure 1 — How this Agreement fits together. A Schedule or Annex prevails over Part A for the User or payment method it covers.
Part A — General Terms
1. Who We Are and How to Reach Us
iSmart International Ghana Limited is a company incorporated in Ghana under the Companies Act, 2019 (Act 992), licensed by the Bank of Ghana as a payment service provider, and operating the iSmartPay platform. In this Agreement we call ourselves “iSmart Ghana”, “we”, “us” or “our”.
| Purpose | Contact |
|---|---|
| Registered office | G-286-2423, Rabat Plot 2 near Gethsemane Cemetery, East Legon, Zaire Street |
| Company registration number | CS681282015 |
| Bank of Ghana licence | PSP Medium |
| General support | Email: info@ismartghana.comsupport and support telephone: 0303944139 |
| Complaints | customersupport@ismartghana.com; see clause 17 |
| Data protection enquiries | The Data Protection Officer at M.MOHAMMED@ismartghana.com; see the Privacy Notice iSG-LEG-00002 |
| Legal notices | The Head of Legal and General Counsel at legal@ismartghana.com and at the registered office |
2. Acceptance and Formation of the Agreement
-
You accept this Agreement when you first do any of the following: create an Account, complete an application we accept, use the Services, or continue to use the Services after we notify you of a change.
-
Acceptance in electronic form is effective. The Electronic Transactions Act, 2008 (Act 772) gives legal effect to agreements formed electronically, and you agree that clicking to accept, or using the Services, has the same effect as a signature.
-
If you accept on behalf of a business, you confirm that you are authorised to bind that business, and “you” means that business.
-
We may decline to enter into or continue a relationship. We are not obliged to give a reason, and where a decline arises from our obligations under the Anti-Money Laundering Act, 2020 (Act 1044) we are prohibited by law from giving one.
-
This Agreement takes effect when we accept your application or when you first use the Services, whichever is earlier, and continues until terminated under clause 16.
3. Eligibility and Verification
We are required by law to identify and verify every User before providing the Services, and to keep that information current for as long as the relationship lasts.
| Requirement | What we ask for | What happens if you do not provide it |
|---|---|---|
| Identity | For an individual: an accepted identity document and a verified mobile number. For a business: registration documents, tax identification, and identification of directors and signatories. | We cannot open the Account, or we must restrict an existing one. |
| Beneficial ownership | For a business: the natural persons who ultimately own or control it, generally at 25% or more. | A refusal to identify beneficial owners is a mandatory decline. We cannot proceed. |
| Screening | We screen you and, for a business, your directors, signatories and beneficial owners against sanctions, politically exposed person and adverse media lists. | A confirmed sanctions match means we must decline or freeze, and we may be prohibited from telling you why. |
| Business activity | A truthful description of what your business actually does. | Processing activity inconsistent with your declared business is a serious breach and may result in immediate suspension. |
| Ongoing information | Updated documents on request, and prompt notice of any change of ownership, control, business activity, address or banking details. | We may restrict the Account until the information is provided. |
You must be at least 18 years old to hold an Account in your own name. The Services are not directed at children.
4. Your Account and Credentials
-
You are responsible for everything done through your Account, whether or not you authorised it, unless you have told us that your credentials are compromised and we have had a reasonable opportunity to act.
-
You must keep credentials, keys, passwords and one-time codes confidential, and you must never share them. We will never ask you for a password, a PIN or a one-time code.
-
You must tell us immediately if you suspect that your Account or credentials have been compromised, using the contact details in clause 1.
-
You must keep your contact details accurate. Notices we send to the details on your Account are effective even if you no longer monitor them.
-
Where the Account is held by a business, you must maintain your own controls over which of your people may act, and you must remove access promptly when a person leaves.
5. The Services
The Services are described in the Schedules and Annexes applicable to you. In summary, we accept, process, record and settle payments; we hold and move stored value where you have a Wallet; and we provide the interfaces, reporting and support connected with those activities.
-
We provide the Services as a payment service provider. We are not a bank, we do not take deposits, and holding a Wallet is not a deposit-taking relationship.
-
We are not a party to the underlying contract between a Merchant and its Customer. We process the payment; the goods or services and any dispute about them remain between them.
-
Some parts of the Services depend on third parties — mobile money operators, acquirers, banks, GhIPSS, card schemes and billers. We remain accountable to you for the Services, and we cannot guarantee the availability or performance of those third parties.
-
We may add, change or withdraw features. Where a change materially reduces the Services, we give notice under clause 19.
6. Transactions
| Rule | Detail |
|---|---|
| Instructions are yours | We act on instructions received through your Account or credentials. Once a Transaction is authorised and submitted, you cannot generally cancel it. |
| Check before you confirm | You are responsible for the accuracy of a destination — a mobile number, an account number, a reference. Value sent to a wrong but valid destination is often unrecoverable. |
| Finality | Mobile money credits and GhIPSS Instant Pay credits are irrevocable once posted. We will attempt a recall where value is misdirected, but a recall is a request that the receiving institution is not obliged to grant. |
| Pending is not success | A Transaction shown as pending has not completed. Do not release goods or services on a pending status. |
| Limits apply | Transaction, daily and balance limits apply. They are set by us, by the Bank of Ghana and by Providers, and they may change without notice where required by law or by a Provider. |
| We may refuse or delay | We may refuse, delay, hold or reverse a Transaction where we are required to by law, where we suspect fraud or financial crime, where a limit is exceeded, where a control requires it, or where a Provider declines it. |
| Records | Our records of a Transaction are the primary evidence of it. We retain them for at least seven years. |
7. Fees, Taxes and Deductions
-
Fees are set out in the fee schedule applicable to you, published separately and forming part of this Agreement.
-
We may deduct fees, refunds, reversals, chargebacks, Reserves, service credits, and any amount you owe us, from amounts we hold for you or from any Settlement. Where we do, the deduction is shown as a separate line on your advice.
-
If amounts we hold are insufficient, you must pay the shortfall on demand. We may set off any amount you owe us against any amount we owe you.
-
All amounts are stated exclusive of taxes and levies unless we say otherwise. You are responsible for your own taxes. We will account for any tax we are required to withhold or collect.
-
Fees for Transactions we have processed are earned when the Transaction is processed, and are not refunded because the Transaction is later refunded, reversed or charged back, unless we say otherwise in a Schedule.
8. Refunds, Reversals and Disputes
-
A refund is initiated by a Merchant and returns value to a Customer. A reversal corrects an error and is initiated by us. A chargeback is initiated by a card issuer under scheme rules.
-
A refund is not instant. Where the original payment was by card, the money typically reaches the cardholder in five to ten working days, and the timing is controlled by the issuer rather than by us.
-
You may not use a refund to move value to a person or destination other than the original payer. Doing so is a serious breach of this Agreement and may be a criminal offence.
-
Where a Customer disputes a Transaction, we will investigate on the transaction record and, for cards, in accordance with the scheme rules. Our determination is made under the framework in iSG-SOP-OPS-00010.
-
Where we have paid an amount to you that is later reversed, refunded or charged back, we may recover it from you by deduction, set-off or demand.
9. Prohibited and Restricted Use
You may not use the Services for any of the following, and doing so entitles us to suspend or terminate immediately.
-
Any activity that is unlawful in Ghana, or that would cause us to breach a law, a licence condition, a scheme rule or a Provider requirement.
-
Money laundering, terrorist financing, sanctions evasion, or any dealing with a sanctioned person or jurisdiction.
-
Processing on behalf of another business — transaction laundering — or processing activity materially different from the business you declared to us.
-
Fraud, including using stolen instruments, testing card numbers, or generating transactions with no genuine commercial purpose.
-
Any business type on our published prohibited category list, which we may change and which is available on request.
-
Attempting to gain unauthorised access to the Services, interfering with their operation, introducing malicious code, or circumventing a limit or a control.
-
Reselling or providing the Services to a third party except as expressly permitted in Schedule 3.
-
Any use that damages, or is reasonably likely to damage, our reputation or our standing with a regulator, a scheme or a Provider.
10. Your Obligations
-
Comply with this Agreement, with all applicable law, and with the scheme and Provider rules that apply to the payment methods you use.
-
Give us accurate information, and tell us promptly when it changes.
-
Maintain your own security, including over your systems, your people and your credentials.
-
Cooperate with any investigation, audit or regulatory enquiry that concerns your use of the Services, and provide information we reasonably request within the time we specify.
-
Where you are a Merchant, deal fairly with your Customers, honour your published refund and cancellation policy, and provide the goods or services you were paid for.
-
Not present yourself as acting for iSmart Ghana, and not use our name or marks except as we permit in writing.
11. Intellectual Property
-
We own, or are licensed to use, the iSmartPay platform, applications, interfaces, documentation, marks and content. Nothing in this Agreement transfers any of it to you.
-
We grant you a non-exclusive, non-transferable, revocable licence to use the Services for the term of this Agreement and for no other purpose.
-
You may not copy, modify, reverse engineer, decompile or create derivative works from the Services, except to the extent the law says you may despite this restriction.
-
You own your own data and your own marks. You grant us a licence to use them only so far as is necessary to provide the Services, to meet a legal obligation, or as permitted in the Privacy Notice.
-
If you give us feedback or suggestions, we may use them freely and without obligation to you.
12. Confidentiality
-
Each party will keep the other’s confidential information confidential, use it only for this Agreement, and protect it with at least reasonable care.
-
Confidential information does not include information that is public through no breach, was already lawfully held, or is independently developed.
-
Either party may disclose where required by law, by a regulator, by a court, or by a scheme, and will where lawful give the other prior notice.
-
Nothing in this clause prevents us from making a report we are required to make under the Anti-Money Laundering Act, 2020 (Act 1044), and we are prohibited from telling you that such a report has been made.
-
These obligations survive termination for five years, and indefinitely for personal data and for trade secrets.
13. Data Protection
We process personal data as a data controller in accordance with the Data Protection Act, 2012 (Act 843). How we do so is set out in the Privacy Notice, iSG-LEG-00002, which forms part of this Agreement and is published alongside it.
-
Where you provide us with personal data about other people — your customers, your directors, your employees — you confirm that you may lawfully do so and that those people have been given the information the law requires.
-
Where we each act as controller in respect of the same personal data, each of us is responsible for our own compliance.
-
Where we process personal data on your instructions rather than for our own purposes, we will do so under a separate data processing agreement.
-
We will each cooperate promptly where a data subject exercises a right, and where a personal data breach affects the other, so that statutory notification periods can be met.
14. Warranties and Disclaimers
-
We warrant that we will provide the Services with reasonable skill and care, in accordance with our licence, and in accordance with the service levels we publish.
-
We do not warrant that the Services will be uninterrupted or error free. Payment systems depend on third parties and on telecommunications, and both fail from time to time.
-
We do not warrant the performance of any Provider, and we do not warrant that a Provider will accept, complete or maintain any particular Transaction.
-
Except as expressly stated, and to the extent the law permits, all other terms, conditions and warranties implied by statute or common law are excluded.
-
You warrant that you have the authority to enter this Agreement, that the information you give us is true, and that your use of the Services is lawful.
15. Liability and Indemnity
This clause allocates risk between us. It does not limit anything the law does not permit us to limit.
| Position | Detail |
|---|---|
| What we never limit | Nothing in this Agreement excludes or limits liability for fraud or fraudulent misrepresentation, for death or personal injury caused by negligence, for a breach of our obligation to safeguard customer funds, or for any liability that cannot lawfully be excluded. |
| What we are not liable for | Indirect or consequential loss; loss of profit, revenue, goodwill, business opportunity or anticipated saving; loss or corruption of your data where you have not maintained your own backups; loss arising from your breach of this Agreement or from your instructions being wrong. |
| Cap on liability | Subject to the first row, our total liability in any twelve-month period is limited to the total fees you paid us in the twelve months before the event giving rise to the claim, or GHS [placeholder] if greater. [Placeholder — to be set by the CFO with counsel and approved under iSG-GOV-00004.] |
| Your indemnity | You will indemnify us against loss, claims, fines and reasonable costs arising from your breach of this Agreement, your unlawful use of the Services, your dealings with your Customers, and any fine or assessment imposed on us by a scheme, a Provider or a regulator because of your activity. |
| Claims | You must notify us of a claim under this Agreement within six months of becoming aware of the circumstances giving rise to it. |
16. Suspension, Restriction and Termination
| Action | When we may take it | Notice |
|---|---|---|
| Restrict a Transaction or a feature | Where a limit is exceeded, a control requires it, a Provider declines, or we suspect error or fraud. | At the time, or as soon as practicable |
| Suspend the Account | Where we suspect fraud or financial crime; where required by law, a regulator, a scheme or a Provider; where a chargeback or dispute ratio is breached; where you breach this Agreement; or where your activity puts customer funds or our licence at risk. | Same day, with the grounds, except where the law prohibits disclosure |
| Withhold settlement or increase a Reserve | Where there is actual or anticipated liability, including chargebacks, refunds, fines or amounts you owe us. | With the settlement advice |
| Terminate for cause | Where a breach is material or is not remedied within the period we specify; where you become insolvent; or where continuing would breach law, licence or scheme rules. | Immediately, with the grounds where the law permits |
| Terminate for convenience | Either party may terminate without cause. | Thirty days’ written notice, unless a Schedule says otherwise |
16.1 What Happens on Termination
-
New Transactions stop. In-flight Transactions are completed, and refunds may still be processed, during a run-off period we specify.
-
We compute a final settlement. We may withhold a Reserve against residual exposure — principally chargebacks, which for cards can arise for up to 180 days after the last Transaction — and release it when the exposure ends.
-
Credentials are revoked, access ends, and any QR or other asset we issued must be returned or destroyed.
-
Where you hold a Wallet, we return your balance to a verified account belonging to you. Where we cannot, we hold it for you as an unclaimed balance and never treat it as our own money.
-
We retain records for at least seven years, and for as long as the law requires.
-
Clauses that by their nature should survive — including fees owed, liability, indemnity, confidentiality, data protection, and dispute resolution — continue after termination.
17. Complaints, Escalation and Disputes
We would rather resolve a problem than argue about it. The route below is designed to be used in order, and nothing in it removes any right you have at law or to approach the Bank of Ghana.
| Stage | What happens | Timeline |
|---|---|---|
| Tell us | Contact us on any channel in clause 1. We log the complaint the day we receive it, whoever receives it. | Same day |
| Acknowledgement | We give you a case reference, the name of the person handling it, and the date by which you will hear from us. | 1 Business Day |
| Investigation and determination | We investigate on the transaction record and give you a determination in plain language, with the reason and what we will do. | Within the timeline published by the Bank of Ghana for payment service providers |
| Internal escalation | If you are not satisfied, ask us to escalate. A senior officer who was not involved reviews it. | 10 Business Days |
| Bank of Ghana | You may complain to the Bank of Ghana. We tell you this in every determination and we will give you the contact details. | At any time |
| Arbitration | A commercial dispute not resolved above is referred to arbitration by a single arbitrator, seated in Accra, conducted in English, under the Alternative Dispute Resolution Act, 2010 (Act 798). The award is final and binding. | On referral |
| Courts | Either party may apply to the courts of Ghana for urgent injunctive relief, or to enforce an award. Otherwise the courts of Ghana have exclusive jurisdiction over any matter not subject to arbitration. | At any time |
Consumers: If you are an individual using the Services for personal purposes, nothing in this clause requires you to arbitrate, and nothing in it prevents you from bringing a claim in the courts of Ghana or complaining to the Bank of Ghana or to the Data Protection Commission.
18. Governing Law
This Agreement, and any dispute or claim arising out of or in connection with it, including a non-contractual one, is governed by and construed in accordance with the laws of the Republic of Ghana.
19. Changes to This Agreement
| Type of change | Notice we give | Your options |
|---|---|---|
| A change that increases a fee, reduces the Services materially, or increases your obligations | At least 30 days before it takes effect | Terminate without penalty before the change takes effect |
| A change required by law, by the Bank of Ghana, by a scheme or by a Provider | As soon as we reasonably can, which may be after it takes effect | Terminate; we cannot waive a change we are required to make |
| A change to a limit for legal, risk or fraud reasons | At the time or immediately after | Contact us to discuss; limits are not negotiable where set by law |
| Any other change, including corrections and clarifications | By publication on the iSmartPay website and in the application | Continue or terminate |
Continuing to use the Services after a change takes effect means you accept it. We keep previous versions and will provide one on request.
20. General
-
Entire agreement. This Agreement is the whole agreement between us about the Services and replaces anything said or written before it, except for any fraudulent statement.
-
Assignment. You may not assign or transfer this Agreement without our written consent. We may assign it, or transfer it as part of a business transfer or reorganisation, on notice to you.
-
Subcontracting. We may use Providers and subcontractors. We remain accountable to you for the Services.
-
Severability. If any provision is held invalid, the rest continues in force and the invalid provision is read down to the minimum extent necessary.
-
No waiver. A failure or delay in enforcing a right is not a waiver of it.
-
Notices. We may give notice by email to the address on your Account, by message in the application, or by publication on the iSmartPay website. You must give notice in writing to the addresses in clause 1.
-
Force majeure. Neither party is liable for a failure caused by an event beyond its reasonable control, including nationwide telecommunications or power failure, civil disturbance, or the act of a government or regulator. This does not excuse an obligation to pay, or our obligation to safeguard customer funds.
-
No partnership. Nothing in this Agreement creates a partnership, agency, joint venture or employment relationship.
-
Third parties. No person other than you and us has any right to enforce this Agreement.
-
Language. This Agreement is made in English, and English governs its interpretation.
Schedule 1 — Merchants
This Schedule applies to you if you are accepted by us to accept payment or make disbursement through the Services. It is in addition to Part A, and prevails over Part A where they conflict.
S1.1 Acceptance and Configuration
-
We decide whether to accept you, on what limits, on what settlement cycle, at what fees and with what Reserve. That decision is made independently of any commercial discussion you have had with us, and we are not obliged to give a reason for a decline.
-
We configure your Account to what we approved. Where something you were told during acquisition cannot be configured, what we confirm at activation prevails, and we will tell you in writing before you go live.
-
You must not go live on a payment method we have not enabled for you.
-
We may require a live test Transaction on each payment method before activation.
S1.2 Settlement
| Term | Detail |
|---|---|
| What you receive | Amounts we collect on your behalf, net of fees, refunds, reversals, chargebacks, Reserves, service credits and any amount you owe us. |
| When | On your settlement cycle, by 14:00 on the cycle date, into the bank account or wallet we have verified as belonging to you. |
| Advice | Every Settlement is accompanied by an itemised advice showing each deduction with its reference. A net figure without a breakdown is not an acceptable advice and you should tell us if you receive one. |
| Verification of your account | We verify your settlement account before the first Settlement and whenever it changes. A change of settlement account requires verification and is a common target for fraud — we will contact you on a known channel to confirm it. |
| Held settlement | We may hold a Settlement where reconciliation is outside tolerance, where there is a suspected error or fraud, where a regulator or Provider requires it, or where your Account is suspended. We tell you and we tell you why, where the law permits. |
| Unclaimed settlement | Where we cannot pay a Settlement to you because your account details are wrong or the account is closed, we hold the amount for you. We never treat it as our own money. |
S1.3 Reserves
-
We may hold a Reserve where your business model, chargeback experience, dispute rate, delivery timescales or financial position create actual or anticipated liability.
-
A Reserve may be a percentage of processing, a fixed amount, or a rolling amount held for a period. We tell you the basis and the period.
-
We may increase a Reserve where risk increases, and we tell you when we do.
-
We release a Reserve when the exposure it covers has ended. For card acceptance this is normally 180 days after your last card Transaction, because chargeback liability survives the relationship.
S1.4 Chargebacks and Disputes
-
You are liable for chargebacks on your Transactions, and for the associated scheme fees, whether or not you were at fault.
-
We will tell you about a chargeback within one Business Day and will tell you what evidence we need and by when. Scheme deadlines are absolute — evidence supplied after our stated deadline cannot be used, however good it is.
-
We may recover a chargeback from amounts we hold, from your Reserve, or from you on demand.
-
We monitor your chargeback ratio. Exceeding published thresholds may result in a remediation plan, an increased Reserve, an extended settlement cycle, restriction of high-risk channels, suspension, or termination.
-
Your billing descriptor must be recognisable to your customers. An unrecognisable descriptor is a leading cause of disputes and we may require you to change it.
S1.5 Your Customers
-
Publish a clear refund, cancellation and delivery policy, and honour it.
-
Do not add a surcharge for a payment method except where the law and the scheme rules permit it.
-
Provide the goods or services you were paid for, when you said you would.
-
Deal with your customers’ complaints promptly. Where a complaint reaches us first, we will pass it to you and we will still log and track it.
-
Never store card numbers, security codes or PINs. If a customer offers you a card number, refuse it.
-
Give your customers a way to contact you that works.
S1.6 Merchant Undertakings and Consequences
| Undertaking | Consequence of breach |
|---|---|
| Process only your own genuine business activity | Immediate suspension; termination; report to Compliance and, where required, to the authorities |
| Do not process for another business | Immediate suspension and termination; scheme and regulatory reporting |
| Keep your declared business activity accurate | Restriction until resolved; re-underwriting; possible termination |
| Maintain your chargeback ratio below the published threshold | Graduated response from notice through Reserve increase to suspension |
| Provide information for audit, investigation or regulatory enquiry within the time we specify | Restriction until provided; possible suspension |
| Keep your systems and people secure | Liability for resulting loss; suspension where our platform or customers are at risk |
| Do not use refunds to move value to a third party | Immediate suspension; report to the MLRO; possible criminal referral |
Schedule 2 — Wallet Holders and Customers
This Schedule applies to you if you hold an iSmartPay Wallet or use the iSmartPay application to pay, receive or hold value. It is written for individuals and is in addition to Part A.
S2.1 Your Wallet
-
Your Wallet balance is money we owe you. It is not a bank deposit and it does not earn interest.
-
We hold funds backing Wallet balances in designated accounts at a partner bank, separate from our own money, and we check every working day that what we hold is at least what we owe.
-
You may load, send, receive, spend and withdraw within the limits of your verification tier.
-
Your Wallet is personal to you. Do not let anyone else use it, and do not use it to hold money for someone else.
S2.2 Verification Tiers and Limits
The more we can verify about you, the more you can do. Limits are set by us and by the Bank of Ghana and we cannot exceed them, however long you have been a customer.
| Tier | What we hold | What it allows |
|---|---|---|
| Tier 1 | Minimum identification consistent with Bank of Ghana requirements | The lowest transaction, daily and balance limits |
| Tier 2 | Full identity verification against an authoritative source | Standard limits |
| Tier 3 | Full verification plus address, source of funds and enhanced checks | The highest limits; approved by our Compliance function |
| Restricted | Applied while we review your Account | You can receive but not send. We may not be able to tell you why. |
Specific limit values are published in the fee and limit schedule and in the application, and may change where the law or the Bank of Ghana requires.
S2.3 Using the Wallet
-
Check the recipient before you confirm. A transfer to a wrong but valid number or account usually cannot be reversed, and getting it back depends on the person who received it agreeing to return it.
-
We will show you the recipient’s name where the receiving institution provides it. If the name is not what you expect, stop.
-
Airtime, data and bill payments are delivered instantly and cannot be cancelled. If you were debited and the service was not delivered, tell us — we refund in full within 24 hours and pursue the biller ourselves.
-
Keep your PIN and one-time codes to yourself. We will never ask for them. Anyone who does is committing fraud.
-
Tell us immediately if your phone or your Account is lost, stolen or compromised.
S2.4 Inactivity, Dormancy and Closure
| Situation | What we do |
|---|---|
| No activity for 6 months | We flag the Wallet as inactive and contact you. |
| No activity for 12 months | We classify the Wallet as dormant, restrict outgoing transactions, and contact you again. Your money remains yours. |
| You come back | We reactivate the Wallet once we have re-verified your identity, normally within two Business Days. |
| You close the Wallet | We return your balance to a verified account belonging to you, normally within five Business Days. |
| We cannot return your balance | We hold it for you as an unclaimed balance under the Bank of Ghana rules. We never treat it as our own money, and your right to claim it does not expire because time has passed. |
| We close the Wallet | We may close on 30 days’ notice, or immediately where the law, a regulator or a serious breach requires. We return your balance in the same way. |
S2.5 If Something Goes Wrong
-
Tell us as soon as you can. Contact details are in clause 1 and in the application.
-
We will log your complaint the day we receive it and acknowledge it within one Business Day with a case reference.
-
We will investigate and give you a determination in plain language within the timeline published by the Bank of Ghana.
-
If you are not satisfied, you may ask us to escalate, and you may complain to the Bank of Ghana at any time. We will give you their contact details.
-
If your complaint is about how we handled your personal data, you may also complain to the Data Protection Commission.
Schedule 3 — Developers and API Partners
This Schedule applies to you if you access the iSmartPay API, the sandbox, or any interface we publish, whether for your own business or on behalf of a Merchant.
S3.1 Access and Credentials
-
Sandbox access is provided for development and testing. The sandbox holds no live value and must never contain real customer data.
-
Production credentials are issued to a named person at an approved Merchant after an integration review, and are personal to that Merchant.
-
Keep credentials server-side. Never place a secret key in client-side code, a mobile application binary, or a public code repository.
-
Tell us immediately if a credential may have been exposed. We revoke first and investigate afterwards, and we will reissue.
-
We rotate production credentials on a schedule whether or not anything has gone wrong.
S3.2 How You Must Build
| Requirement | Why |
|---|---|
| Send an idempotency key on every value-moving call | A retried request must not move money twice. Without a key we cannot protect you from this. |
| Treat pending as non-terminal, and never infer success from a timeout | A timeout tells you nothing about whether value moved. Query the status instead. |
| Verify the signature and timestamp on every webhook | Otherwise you will accept forged or replayed events. |
| Process webhook events once, by event identifier | Delivery is at-least-once. You will receive duplicates and must handle them. |
| Be able to query Transaction state by API | Webhook delivery is not guaranteed. An integration that depends on webhooks alone will eventually miss a Transaction. |
| Never store card numbers, security codes or PINs | Doing so breaches PCI DSS and may expose you and us to scheme sanction. |
| Collect only the personal data the Transaction requires | Data minimisation is required by the Data Protection Act, 2012 (Act 843). |
| Surface our reason codes rather than a generic failure | Your users and our support both need to know what actually happened. |
S3.3 Rate Limits, Versions and Change
-
Rate limits apply by tier and are published. Exceeding them returns an error with a retry-after value which you must respect.
-
We ship additive changes within the current API version without notice. They will not break a correct integration.
-
A change that would break a correct integration is released as a new version, and we give at least 90 days’ notice before retiring the old one.
-
We retire an old version only when traffic on it has reached zero. We will contact you at 60, 30 and 7 days if you have not migrated.
-
Where a security fix requires an immediate breaking change, we will make it and tell you as soon as we can.
S3.4 Acceptable Use of the Interfaces
-
Do not use the API to test card numbers, enumerate accounts, or probe for weaknesses without our written authorisation.
-
Do not scrape, mirror or resell our data or the Services except as we permit in writing.
-
Do not misrepresent your integration as an iSmart Ghana product, or use our marks without permission.
-
Do not circumvent a limit, a control or a version retirement.
-
We may suspend credentials immediately where use threatens the platform, other users, or customer funds.
Annexes — Payment Method Terms
These Annexes apply according to the payment method used. They are in addition to Part A and to the applicable Schedule, and prevail over both for that payment method.
Annex A — Mobile Money
-
Transactions are executed by mobile money operators. Their availability, limits and rules apply and we do not control them.
-
A credit to a mobile money wallet is irrevocable once posted. Where value is misdirected we will raise a recall the same working day, but the receiving operator and the recipient are not obliged to return it.
-
Where the operator supports it, we validate the recipient name before dispatch and show it to you. Where a name does not match, the Transaction is stopped and we will not release it on assumption.
-
Recipient wallet tier limits apply at the receiving end. A payout can fail because the recipient cannot receive the amount, and we will tell you that is the reason.
-
A Transaction shown as pending is not complete. Do not release goods against a pending status.
Annex B — Card Acceptance
-
Card acceptance is subject to the operating rules of the card schemes and to the requirements of our sponsoring acquirer. Those rules bind us and, through this Agreement, bind you.
-
You must comply with PCI DSS to the level applicable to you, and must never store card numbers, security codes or PINs.
-
Authorisation reserves funds; capture claims them. They are separate events and a successful authorisation is not a completed payment.
-
We may require 3-D Secure on card-not-present Transactions. Where authentication succeeds, fraud liability generally shifts to the issuer; where you choose to proceed without it and we permit that, it does not.
-
Chargeback rules, deadlines and ratio thresholds are set by the schemes. Deadlines cannot be extended by us or by you.
-
A refund to a card typically reaches the cardholder in five to ten working days. That timing is set by the issuer and we cannot accelerate it.
Annex C — Bank Transfer and GhIPSS Instant Pay
-
Inbound payments are identified by the virtual account or unique reference we allocate to you. Payments that arrive without a usable reference cannot be attributed automatically.
-
Where we cannot identify an inbound payment, we hold it as an unapplied credit. We never apply it on probability and we never treat it as our own money. We will return it to the remitter where we can identify them.
-
You must not give out a virtual account or reference we have retired, and you must not reuse one for a different payer.
-
For outbound payments we run a GhIPSS account name enquiry before every credit. A name mismatch stops the item and it cannot be released by instruction.
-
A GhIPSS Instant Pay credit is irrevocable once posted. A recall is a request the receiving bank is not obliged to grant.
-
GhIPSS operates within defined windows and ACH runs in cycles. An instruction given outside a window is queued for the next one rather than failed.
Annex D — Scan-to-Pay and QR
-
QR assets we issue to you remain controlled instruments. We record every one, and you must not copy, alter, relocate or reproduce an asset without telling us.
-
Check your displayed QR assets regularly for tampering or substitution. Replacing a merchant’s QR sticker with another is a known fraud, and it is invisible at the moment of payment to both you and your customer.
-
Tell us the same day if customers report paying and you have not received the money. We will deactivate the assets at that location immediately while we investigate.
-
Value moves over the underlying payment method the customer chooses, and that method’s Annex applies to the Transaction.
-
On termination we deactivate every asset issued to you, and you must return them or confirm in writing that they have been destroyed.
Annex E — Wallet Services
-
Wallet terms for individuals are in Schedule 2. This Annex applies where a Merchant uses wallet functionality as part of its own service.
-
Value held is a liability we owe, backed one-for-one in designated accounts and verified daily.
-
Tier limits apply to every wallet and cannot be exceeded by agreement.
-
We may restrict a wallet where transaction monitoring requires it. Where we do, we may be prohibited by law from explaining why.
Annex F — Invoicing, Subscriptions and Payout Automation
-
You must hold a valid mandate from the payer before any recurring collection, and you must be able to produce it. We will ask for it if the payer disputes a charge.
-
A cancellation takes effect from the moment it is requested, not at the end of a billing period. A schedule cancelled by the payer cannot be restarted by you — a fresh mandate is required.
-
Any collection taken after a valid cancellation is refunded in full, without argument, and we may recover it from you.
-
Retries following a failed collection are bounded and spaced. We do not permit same-minute or same-hour retries.
-
For payout runs, we confirm each item individually. Aggregate run success is not evidence that any particular beneficiary was paid, and you should not treat it as such.
-
We may require you to approve control totals before a run is dispatched, and we will not dispatch a run whose totals differ from what was approved.
Annex G — Value-Added Services
-
Airtime, data, bill payments and similar services are fulfilled by third-party billers. The service purchased is theirs, not ours.
-
We validate the destination with the biller before taking a debit, and we show you the account name where the biller returns one.
-
Fulfilment is instant and cannot be reversed. A top-up sent to a mistyped number is generally unrecoverable.
-
If you are debited and the service is not delivered, we refund you in full within 24 hours of establishing non-fulfilment. Recovering the money from the biller is our problem, not yours.
-
We may remove a biller from service without notice where its failure rate makes it unreliable.
Fee, Limit and Reserve Schedule
Fee, Limit and Reserve Schedule
Fees, limits and Reserve terms specific to you are set out in the schedule we issue at activation and publish in your Account. The framework below explains how they work. Specific values are placeholders in this draft and require approval under iSG-GOV-00004 before publication.
| Item | Basis | Notes |
|---|---|---|
| Transaction fee | Percentage of value, fixed amount, or both, by payment method | Charged when the Transaction is processed |
| Settlement fee | Fixed amount per Settlement, where applicable | Deducted from the Settlement |
| Refund handling fee | Fixed amount per refund, where applicable | The original Transaction fee is not returned |
| Chargeback fee | Fixed amount per chargeback, plus any scheme fee | Charged whether or not the chargeback is later won |
| Failed payout fee | Fixed amount per failed item, where applicable | Not charged where the failure was caused by us |
| Reserve | Percentage of processing, fixed amount, or rolling amount | Released when the exposure ends; card Reserves normally 180 days after the last card Transaction |
| Transaction, daily and balance limits | Set by tier, by risk rating, and by regulation | May change without notice where required by law or a Provider |
| Late payment | Interest on overdue amounts at [placeholder] per annum | Applies to amounts you owe us that remain unpaid after demand |
Acceptance
Acceptance
By creating an Account, completing an application we accept, or using the Services, you confirm that you have read and understood this Agreement, that you accept it, and that you are authorised to accept it on behalf of any business for which you act.
| Item | Detail |
|---|---|
| Document reference | iSG-LEG-00001 |
| Version | 1.00 — draft for legal review |
| Effective date | [To be inserted on approval] |
| Published at | [iSmartPay website URL] and within the iSmartPay application |
| Previous versions | Available on request from the Head of Legal and General Counsel |
| Incorporated documents | The Privacy Notice (iSG-LEG-00002); the fee, limit and Reserve schedule issued to you; any product Annex applicable to a payment method you use |
Regulatory and Statutory Framework
Regulatory and Statutory Framework
This Agreement is written against the following instruments. Where any provision of this Agreement conflicts with a mandatory requirement of Ghanaian law or of a Bank of Ghana directive, that requirement prevails and this Agreement is read accordingly.
| Instrument | Relevance to this Agreement |
|---|---|
| Payment Systems and Services Act, 2019 (Act 987) | Authorises iSmart Ghana to provide payment services under its licence; requires customer funds to be safeguarded and segregated; governs transaction integrity, incident reporting, outsourcing accountability and the production of records to the Bank of Ghana. |
| Bank of Ghana Guidelines for Payment Service Providers and Electronic Money Issuers | Set tier thresholds and transaction limits, merchant governance requirements, consumer protection and complaint handling timelines, daily reconciliation of customer float, and cyber and information security directives. |
| Data Protection Act, 2012 (Act 843) | Governs the collection, use, disclosure, transfer and retention of personal data; establishes the rights of data subjects and the supervisory role of the Data Protection Commission; requires registration of data controllers. |
| Electronic Transactions Act, 2008 (Act 772) | Gives legal effect to electronic contracts, electronic records and electronic signatures; governs the formation of agreements accepted online or in an application. |
| Anti-Money Laundering Act, 2020 (Act 1044) and Anti-Terrorism Act, 2008 (Act 762) | Require customer due diligence before a relationship begins, ongoing monitoring, sanctions and PEP screening, reporting of suspicion to the Financial Intelligence Centre, and prohibit disclosing that a report has been made. |
| Alternative Dispute Resolution Act, 2010 (Act 798) | Governs arbitration seated in Ghana, including the constitution of the tribunal, the conduct of proceedings and the enforcement of awards. |
| Companies Act, 2019 (Act 992) | Governs the corporate existence, authority and capacity of iSmart International Ghana Limited to contract. |
| Card scheme operating rules (Visa, Mastercard) and GhIPSS scheme rules | Govern card acceptance, authorisation, capture, chargebacks and interbank transfer; these rules bind iSmart Ghana and, through it, merchants accepting those instruments. |
Abbreviations and Acronyms
Abbreviations and Acronyms
| Abbreviation / Acronym | Description |
|---|---|
| ADR | Alternative Dispute Resolution |
| AML | Anti-Money Laundering |
| API | Application Programming Interface |
| BoG | Bank of Ghana |
| CDD | Customer Due Diligence |
| CFT | Combating the Financing of Terrorism |
| CX | Customer Experience |
| DPA | Data Protection Act, 2012 (Act 843) |
| DPC | Data Protection Commission |
| DPO | Data Protection Officer |
| EDD | Enhanced Due Diligence |
| EMI | Electronic Money Issuer |
| FIC | Financial Intelligence Centre |
| GhIPSS | Ghana Interbank Payment and Settlement Systems Limited |
| GhQR | Ghana Quick Response code — the national interoperable QR specification |
| GHS | Ghana Cedi |
| GIP | GhIPSS Instant Pay |
| ISO | International Organization for Standardization |
| KYB | Know Your Business |
| KYC | Know Your Customer |
| MLRO | Money Laundering Reporting Officer |
| MMO | Mobile Money Operator |
| MoMo | Mobile Money |
| MSISDN | Mobile Station International Subscriber Directory Number |
| NOC | Network Operations Centre |
| PAN | Primary Account Number |
| PCI DSS | Payment Card Industry Data Security Standard |
| PEP | Politically Exposed Person |
| PSP | Payment Service Provider |
| PSSA | Payment Systems and Services Act, 2019 (Act 987) |
| RCA | Root Cause Analysis |
| SLA | Service Level Agreement |
| SOP | Standard Operating Procedure |
| STR | Suspicious Transaction Report |
| T&Cs | Terms and Conditions |
| TAT | Turnaround Time |
| TSP | Technology Service Provider |
| VAS | Value-Added Services |
Definitions
| Term | Description |
|---|---|
| Account | The record maintained by iSmart Ghana of a User’s relationship with the Services, including any Wallet, merchant record, credentials and settings. |
| Acquirer | The regulated entity that maintains the merchant relationship, accepts card or wallet transactions on the merchant’s behalf and bears settlement risk. iSmart Ghana operates as a Payment Service Provider under sponsorship and settlement arrangements with its partner banks and mobile money operators. |
| Agreement | These Terms and Conditions together with every Schedule, Annex, published fee schedule and any order form or application accepted by iSmart Ghana. |
| Beneficial Owner | A natural person who ultimately owns or controls a merchant, or on whose behalf a transaction is conducted. Under the Anti-Money Laundering Act, 2020 (Act 1044) a shareholding or voting interest of 25% or more triggers beneficial ownership identification. |
| Business Day | A day other than a Saturday, Sunday or public holiday in Ghana on which banks are open for general business in Accra. |
| Cardholder Data | The primary account number (PAN) alone or together with cardholder name, expiration date and service code, as defined by PCI DSS. |
| Chargeback | A forced reversal of a card transaction initiated by the issuing bank on behalf of a cardholder under scheme dispute rules, resulting in funds being debited from the acquirer and recovered from the merchant. |
| Customer | A person who pays a Merchant, or who receives value, through the Services. |
| iSmart Ghana | iSmart International Ghana Limited, a company incorporated in Ghana and licensed by the Bank of Ghana as a payment service provider. |
| iSmartPay | The payment platform, applications, interfaces and services operated by iSmart Ghana under that name. |
| Merchant | A business, institution or individual accepting payments through iSmartPay under an executed Merchant Services Agreement. |
| Personal Data | Data about an individual who can be identified from that data or from that data together with other information in the possession of the data controller, as defined in section 96 of the Data Protection Act, 2012 (Act 843). |
| Provider | A mobile money operator, acquirer, bank, GhIPSS, card scheme, biller or other third party through which a Transaction is executed. |
| Reconciliation | The control process of matching iSmartPay internal transaction records against partner, scheme and bank statements to confirm completeness, accuracy and validity of value movement. |
| Refund | A merchant-initiated return of value to a payer for a transaction that was successfully authorised and captured, whether in full or in part. |
| Reserve | An amount withheld from settlement by iSmart Ghana against actual or anticipated liability, including chargebacks, refunds and fees. |
| Reversal | The cancellation of a transaction that has not been fully completed or settled, restoring the payer and merchant to their pre-transaction financial position. |
| Services | The payment and related services made available by iSmart Ghana through iSmartPay, as described in these Terms and the applicable Schedules and Annexes. |
| Settlement | The transfer of net funds owed to a merchant from iSmartPay settlement accounts to the merchant’s designated bank or wallet account after deduction of fees, holds and recoveries. |
| Suspicious Transaction | A transaction which, having regard to its nature, complexity, value, pattern or the circumstances of the parties, gives reasonable grounds to suspect money laundering, terrorist financing or another predicate offence, and which is reportable to the Financial Intelligence Centre. |
| Transaction | Any payment, collection, disbursement, transfer, refund, reversal or other movement of value initiated or processed through the Services. |
| Transaction Exception | Any transaction that does not complete its expected lifecycle or that fails a control check, including stuck, orphaned, duplicated, unmatched, partially settled and mis-posted transactions. |
| User | Any person who accesses or uses the Services, including a Merchant, a Customer, a Wallet holder and a Developer. |
| Wallet | Stored value held by iSmart Ghana for a Customer on the iSmartPay platform, representing an amount iSmart Ghana owes that Customer. |